KUALA LUMPUR — As the average life expectancy of Malaysians rise, the pressing question becomes whether they are equipped financially to live past retirement.
Based on Malaysia’s latest official figures, babies born in 2026 are expected to live to 75.5, while a person aged 60 and 65 now are expected to live to 80.2 and 81.5 respectively.
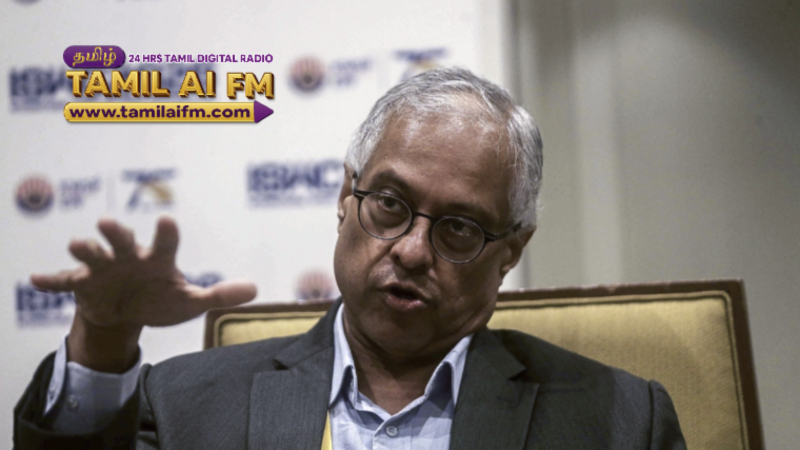
In an interview with Malay Mail, licensed financial planner Rajen Devadason said, “But what are you going to do if you live to be 85, 90, 95, 100, 105?”
In planning for your retirement finances, Rajen said you could split your net income (after paying taxes) into three portions of about 33 per cent each:
- Past (Money that you have already spent, but are paying now = Existing debts, e.g. housing loan, car loan)
- Present (Current expenses = What you have to pay for today)
- Future (What you have to invest now for the future)
“You should probably commit one third to pay your debts, try and accelerate that, get rid of those as fast as possible; one third to take care of your middle section, your current expenses; and one third for tomorrow,” he told Malay Mail at the Employees Provident Fund’s (EPF) recent International Social Wellbeing Conference 2026 (ISWC 2026).
If you are currently contributing 11 per cent to your EPF retirement savings, Rajen said this means you would need to put aside about another 22 per cent into sources that can generate passive income for the future.
Once you have cleared off your debts, you can then spend half of your income on current expenses and preparing for the future, he suggested.
Rajen said he gives this advice to his clients too: “Then it’s really up to them. They’re the ones who are going to have to work on their budget. They need to have a written budget.